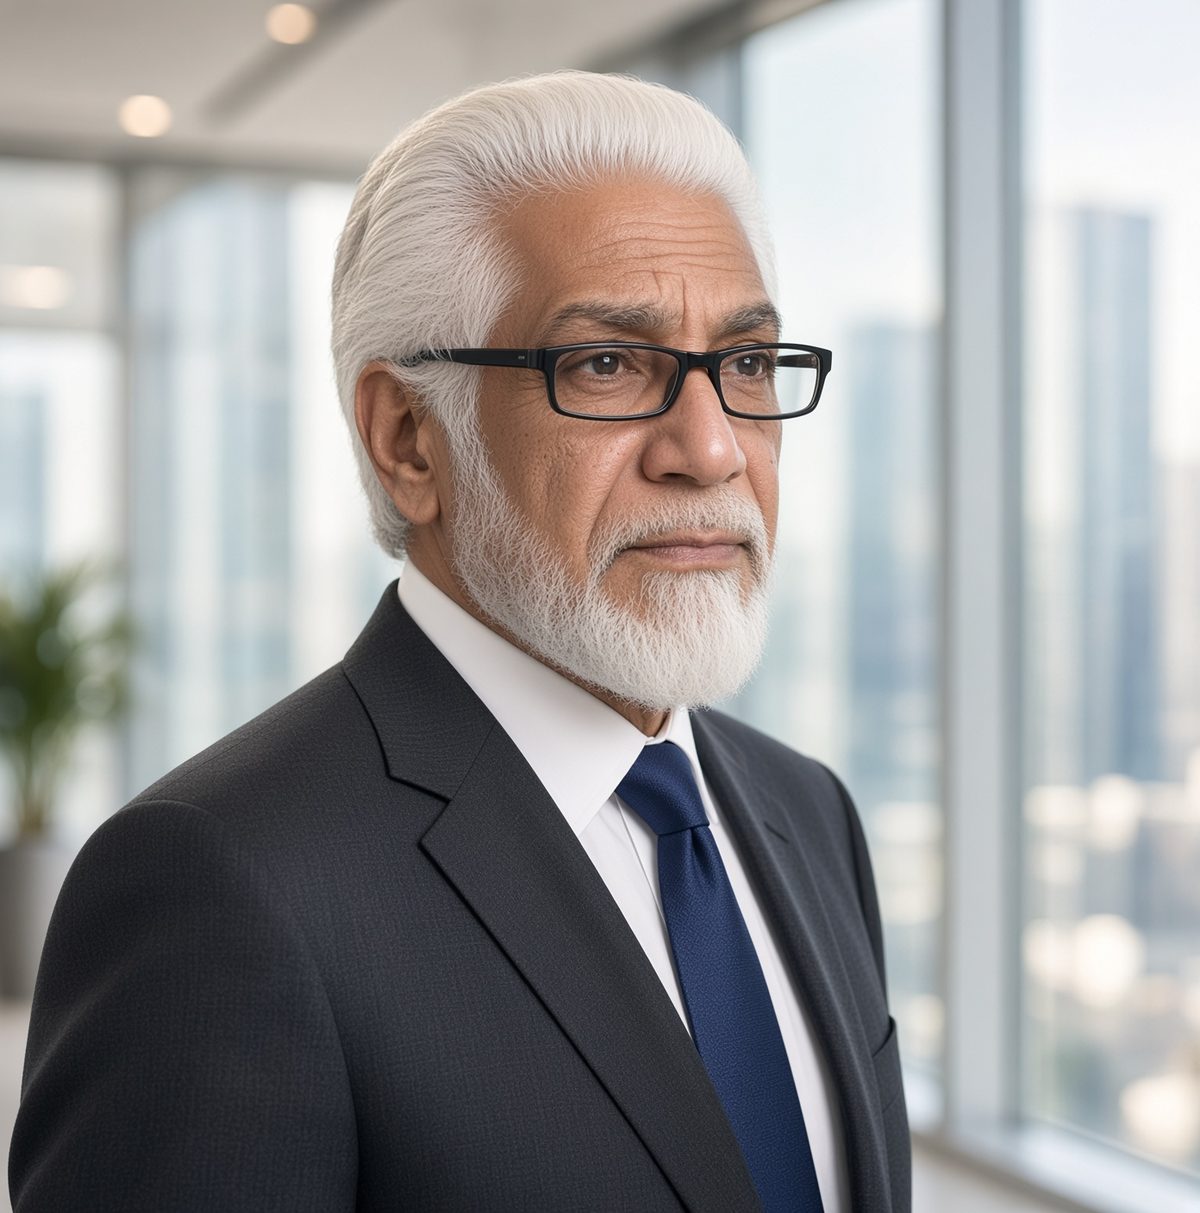
Anil Rattan

About · Financial planner for 28 years

Anil Rattan

Most of his working life has been spent across a table from a family, a pen in hand and a sheet of numbers between them, going over each line until it makes sense to the people who will be paying for it.

How he thinks

He starts by asking what the money is for.

Anil rarely begins with a product. He begins with a question: what do you actually want your money to do? For almost every household the answer comes down to two things. If something happens to the person who earns, the family should be looked after. And separately, there should be savings that have time to grow, for a child’s education, for retirement, for the years when earning slows down.

Over 28 years he has seen how often those two aims are bought as unrelated products, at different times, from different conversations, with no one ever laying them next to each other. A family ends up paying for several things without a clear picture of what they add up to, when the payments end, or what will come back and when.

His work is to put that picture together. Life insurance carries the protection. Mutual funds, planned alongside it, carry the long-term growth. The point is not to sell both; it is to show how they relate, so that the plan a family signs is one they can explain to each other at home.

His method

Where the hours across the table actually go.

There is no fixed script, but the conversation tends to move through the same ground, in roughly this order.

First

Protection, sized for the family.

The first question is what would happen to the household if the main income stopped. Life insurance answers that, and Anil treats it as the foundation everything else rests on. He talks through what the cover is meant to do for the people who depend on you, rather than starting from a premium figure and working backwards.

He is also clear about what a policy is and is not. The benefits of any life insurance plan depend on its terms, so he goes through those terms in ordinary language: what is covered, what is paid out, and on what conditions. If a part of the policy document is not clear to you, it is not clear yet, and he will keep going until it is.

Then

The way you pay, decided as carefully as the plan.

In Anil’s experience, a plan rarely fails because the product was wrong. It fails because the premium became hard to keep up. So he spends real time on how you will pay, and usually lays out two paths side by side.

One is a very small premium, low enough to sit comfortably inside a monthly budget year after year. The other is a larger premium paid for only a limited number of years, after which nothing more is due. Some families like the lightness of the first; others would rather pay more now and be finished. Neither is automatically better. The better path is the one your household can actually sustain, through good years and tight ones, and he will say so plainly.

Compare the two paths →

Alongside

Growth that works toward the same goals.

Once the protection is settled, he looks at long-term savings through mutual funds, placed next to the insurance rather than in a separate drawer. The two are meant to point at the same goals, so that you can see how the protection you pay for and the money you set aside for growth fit into one household plan.

He is careful to explain that the two behave differently. Life insurance benefits follow the policy terms. Mutual funds are subject to market risk: their value can rise and fall, and past movement says nothing certain about the future. He would rather you understand that before you begin than discover it in a difficult year.

On paper

Every year, on its own line.

This is the part people tend to remember. Anil lays a plan out year by year: what you pay in each year, the year the payments stop, and what the illustration shows coming back later, including the quiet years in between when nothing much happens. Seeing those quiet years is part of understanding a plan honestly.

One worked example he often uses is Rs 320 a day, for 12 years, towards a crore. It is an illustration, not a quote or a promise, and it is there to show the shape of an idea: a modest, regular amount paid for a limited time, building toward a larger figure over the life of the policy. In that illustration the premium is also described as qualifying for a tax rebate, though tax rules change and depend on your own circumstances. Plans can also illustrate a lifetime pension and the amounts that mature over the years.

He uses the sheet as a teaching tool, not a sales slide. Nothing is tucked away in jargon, and you are welcome to stop him at any line and ask why.

Open the year-by-year sheet →

If you are already insured

A second reading of the policy you hold.

Many people already hold a life insurance policy and are not entirely sure what it does. They know the premium, perhaps, but not when the payments end, what the cover amounts to, or when money is due to come back. Anil will sit with that policy and go through it with you, free of charge.

In practice that means reading it together: the cover it provides, the premiums and how long they run, the dates when payments are due, the points at which money may come back, and anything in the wording that is unclear. The aim is that you leave understanding your own policy. It is not a conversation designed to talk you out of it or into something else.

Through all of it, the rule he works by is simple: each part is explained before anything is signed. If that takes a second meeting, or a third, that is time well spent.

Beyond the work

Outside the planning, he sings classical music.

Away from the numbers, Anil sings classical music. It asks for the same patience his work does, and it is a reminder that he is a person first, someone you can simply call and talk to.

You can reach him directly, whichever is easier for you.

WhatsAppEmail

Read the planning page

Contact

Bring the policy, or just the question.

There is no rush. Send a WhatsApp message or an email whenever it suits you. If your question is about a life insurance policy you already hold, the advice is free.

WhatsAppEmail

Get in touch